


A few weeks ago I was having dinner with a group of friends who are just as passionate about investing as I am. At some point the conversation shifted to interesting opportunities, and one of them mentioned an American company in the oil and gas space that seemed rather unremarkable at first glance but immediately stood out once he shared its numbers. A company with 26% profit growth over the past 10 years, an 87% EBITDA margin, a 65% free cash flow margin and no net debt. It sounded just too good to be true.
The company he was referring to was Texas Pacific Land Corporation (TPL). I wrote the name of the company down that evening and decided to take a closer look at it once I had time. Four weeks later that brings us to this deep dive on this extraordinary company, in which we will break down the business, evaluate its prospects and see at which price the stock might be worth a buy.
That being said, let’s dive in!
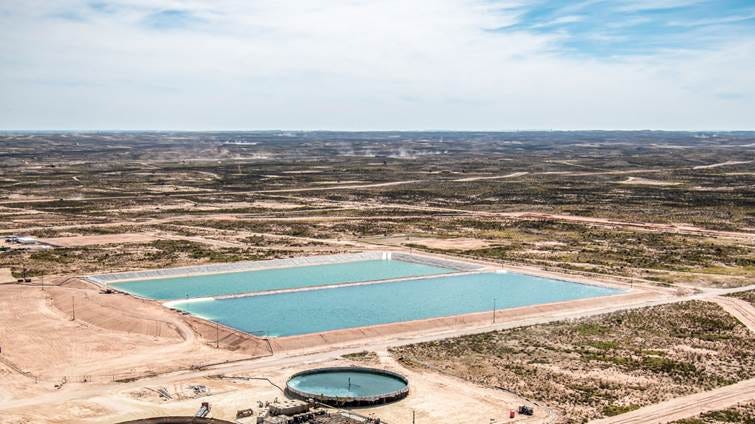
What’s the business behind TPL?
A look at the company’s history shows that Texas Pacific Land has been around for a very long time. Its origins go back to 1888, when the Texas and Pacific Railway went bankrupt and transferred large areas of land into a newly created trust. For decades the trust mainly held the land, collected small payments and occasionally sold parts of it. It was quiet, slow moving and far from what most people would consider a growing business.
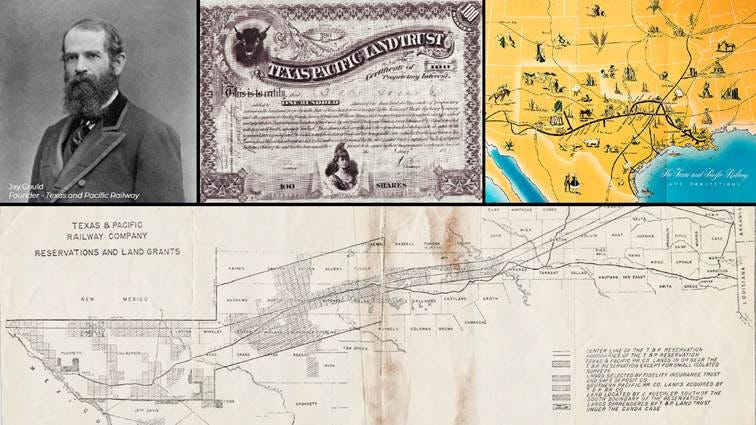
What no one could know at the time was how valuable this land would become one day. Texas Pacific Land owns 873,000 acres in the Permian Basin in western Texas, land that later turned out to be one of the most oil and gas rich regions in the United States.
The real shift began in the early 2010s. New drilling technology made it possible to reach oil and gas trapped in dense shale layers.
Horizontal drilling and hydraulic fracturing opened the door to large scale development across the Permian. Operators could finally access areas that had been unreachable for decades, and with this change completely new income opportunities appeared for Texas Pacific Land.
Around the same time the company reorganized its leadership. In 2011 Tyler Glover became CEO and started building a team focused on creating long term value from the land. The company moved away from simply holding acreage and began to build a business model around monetizing both the surface and the resources below it. Employees at TPL sometimes joke that they might be working for the oldest start up they have ever seen, because the company only truly began to grow once the potential of the region became obvious.
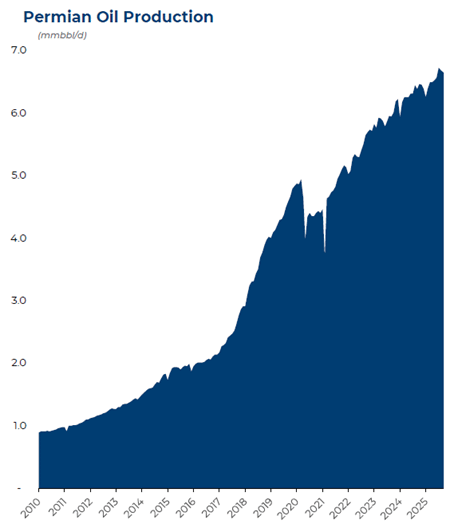
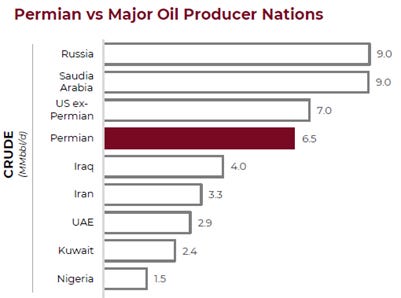
Before we look deeper into the company itself, it helps to understand the region where all of this takes place. The Permian Basin stretches across western Texas and southeastern New Mexico and has become the most productive oil region in the United States. Production reached record levels in recent years and today accounts for roughly 40-45% of total US oil output. But even on a global stage the Permian Basin plays an important role, driven by its strong geology, good infrastructure and the continuous investments of major operators.
With this context in mind the company’s structure becomes easier to understand. Texas Pacific Land does not drill for oil or gas. Instead it earns money because it owns the land on which the drilling activity takes place and because it holds extensive royalty rights. Through these rights the company earns a share of revenue for every barrel of oil and every cubic foot of gas sold by the operators. Through its surface rights TPL receives payments whenever operators build roads, lay pipelines, run power lines, access drilling locations or use the land for commercial purposes. It is worth noting that surface rights and royalty rights are held separately and independently, which means TPL often earns money even when infrastructure is built across its land to serve wells located elsewhere.
Another important business for TPL is water, which the company began building around 2017. Drilling for oil requires large amounts of water, and every producing well creates wastewater that must be transported, treated or disposed. TPL recognized early that it could support operators by providing fresh water, moving it across its land and handling the produced water that comes to the surface during production. This area has grown quickly and now forms a key part of the company’s operations.
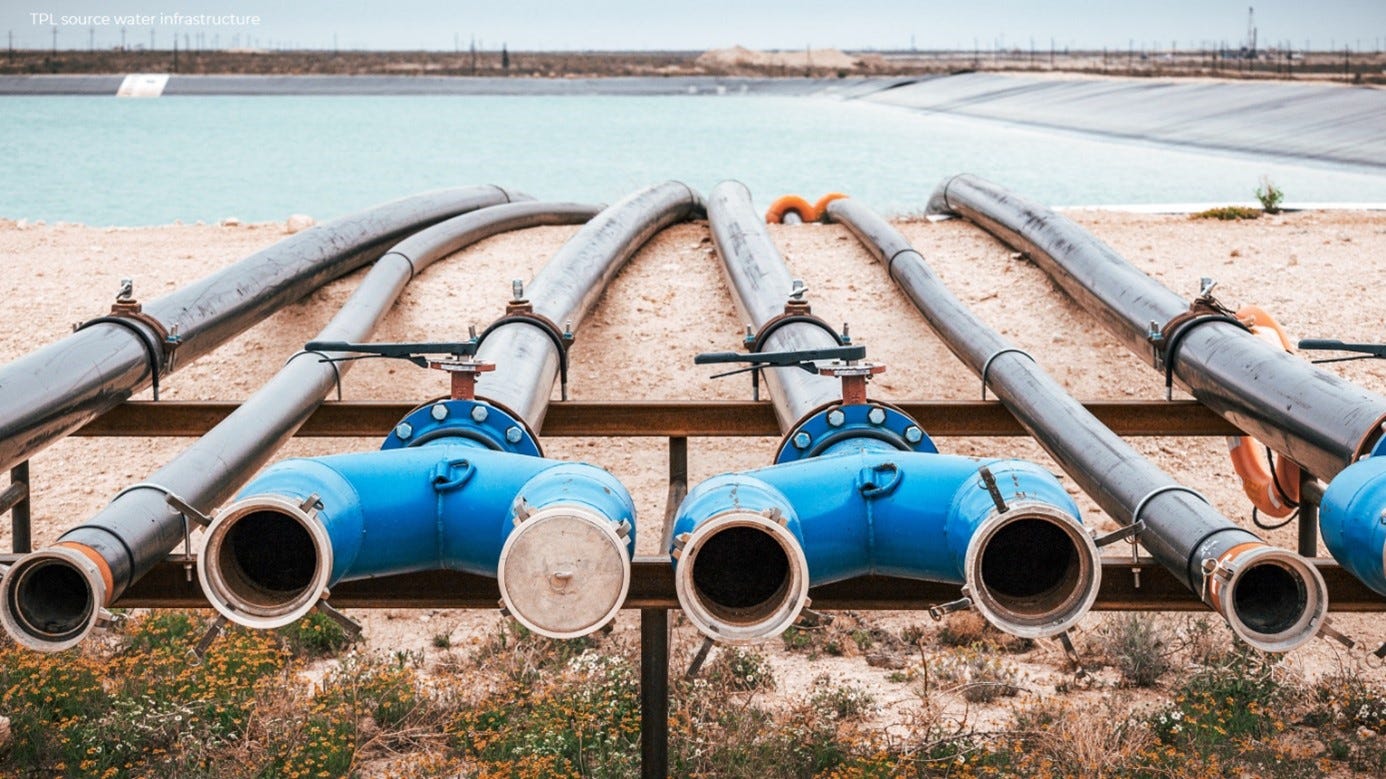
All of these activities can be grouped into two official segments. The first is Land and Resource Management, which includes royalties, land leases, long term payments for pipelines and other infrastructure, commercial leases and the sale of materials such as caliche and sand. This segment accounts for about 63% of total revenue and is driven mainly by oil and gas royalties. The second is the Water Services and Operations segment, which includes the supply, transport and handling of water used throughout the drilling and production cycle. This segment accounts for about 37% of total revenue and has become increasingly important as activity in the basin expanded.
Now that we have a first overview of the business model, it is time to ask what truly sets TPL apart and whether the company actually has a competitive advantage.
Does Texas Pacific Land Have a Moat?
When I first looked at Texas Pacific Land’s business model, one question came up immediately. Why does the Permian Basin offer better conditions for drilling than so many other regions, and does TPL actually have a moat within this environment? To answer that, it helps to step back and look at the wider competitive landscape, because oil companies like Exxon, Chevron or BP constantly battle for the most productive and lowest cost acreage available.
The Permian Basin stands out for several reasons. Its geology is unusually favorable, with multiple stacked layers of oil and gas bearing rock that can be accessed from a single drilling site. Modern horizontal drilling allows operators to reach several of these layers from one pad, which means higher productivity and more flexibility. It also gives operators the flexibility to ramp activity up or down depending on market conditions, which helps them maintain higher profitability. At the same time the investment costs and lead times for shale wells are far lower than for large offshore projects, making the region much easier to manage through different price cycles. Combined with a dense network of pipelines, refineries and roads that move oil and gas efficiently to the ports along the Gulf Coast the region offers some of the lowest breakeven costs in the industry.
Political stability and predictable regulations in the United States add another layer of security that many international regions cannot match.
Competition exists both inside and outside the Permian. In the US, other shale regions such as Eagle Ford or Bakken also offer good drilling opportunities, but overall they cannot match the productivity, scalability and cost advantages that the Permian provides. Internationally, certain offshore regions like Guyana or Brazil can compete on cost per barrel, and the Middle East remains unmatched in pure production economics. Yet shale development follows its own logic. Operators value fast payback periods, short project cycles and the ability to react quickly to oil price changes. Under those conditions the Permian usually comes out on top, which is why capital continues to flow into the basin year after year.
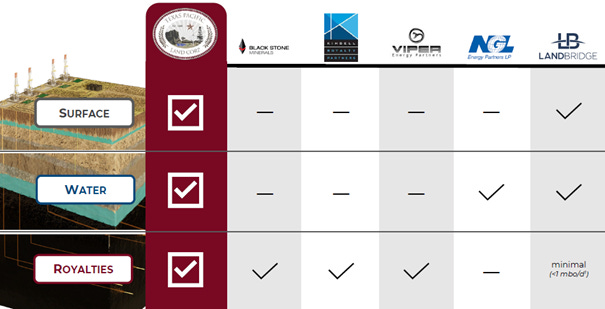
Looking at activity inside the Permian Basin shows that several other companies are active there as well. On the royalty and mineral side, peers include Sitio Royalties, Viper Energy Partners, Kimbell Royalty Partners and Black Stone Minerals. These businesses share the same basic idea of receiving a percentage of production without drilling themselves. The difference is that TPL controls both surface rights and royalty interests, which opens far more ways to monetize activity. On the surface and water side, regional competitors include LandBridge, WaterBridge, NGL Energy Partners and a few others. They operate parts of the value chain, but none offer operators the full range of services and land access that TPL provides. This one stop setup is a clear competitive advantage because operators can secure mineral rights, surface use, water supply, disposal solutions and long term infrastructure rights from a single partner instead of coordinating with multiple landowners.
Another important element is the lock in effect that comes with operating on TPL land. Once a company decides to lease acreage and drill, it enters several long running agreements that make a later move unlikely. Mineral leases typically run for a few years and then continue automatically as long as production remains active. Easements for pipelines and power lines are even longer, often lasting for several decades. Water and surface use agreements also run over multiple years. Together these contracts create a long term commitment that keeps operators tied to the area.
In summary the Permian Basin stands out because it combines highly favorable geological characteristics, flexible development, strong infrastructure, political stability and some of the lowest production costs in the world. This mix explains why operators focus so heavily on this region, and as we have seen, TPL is the largest and, more importantly, the most comprehensive land and royalty holder in the area.
Now that we understand the company’s competitive advantages, the question becomes whether they can actually be translated into growth.
So what about growth?
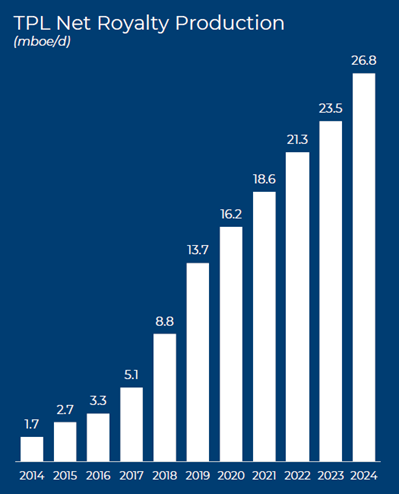
As mentioned in the first chapter, Texas Pacific Land may be more than a century old on paper, but real growth only began in the early 2010s. With drilling activity in the Permian accelerating, production on TPL land increased sharply and earnings compounded at an average rate of roughly 32% per year.
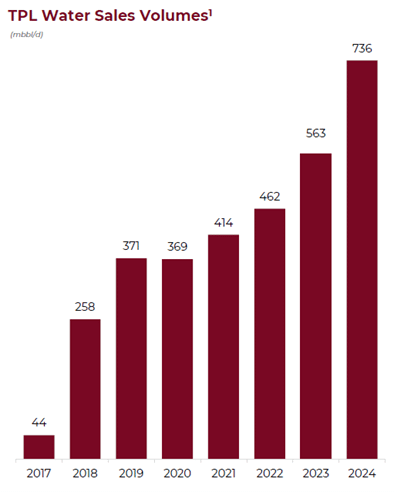
The launch of the water business around 2017 added an additional growth pillar and pushed the company even further. It looked more like a young, fast growing operator than a historic landholder. Today the company moves into a more mature phase, and the question becomes how growth might evolve from here.
To understand what comes next, it helps to remember that TPL operates with a fixed land base. The business is not infinitely scalable, because activity can only take place on the land the company holds and acquisitions of additional acreage are possible only to a limited extent. Growth therefore depends on two core variables: the level of drilling activity on this land and the price operators receive for the oil and gas they produce.
As a reminder, TPL earns a percentage of the revenue operators generate from selling oil and gas, which means its income moves directly with both the volume produced and the price at which it is sold. When drilling expands, royalty volumes rise, the water business grows because more water must be supplied and processed and because more surface infrastructure needs to be built and maintained. When activity slows, these streams soften accordingly. In total roughly 85% of TPL’s revenue is variable and depends on both production volumes and prices.
But how constrained is growth by the physical limits of TPL’s land. According to the U.S. Geological Survey the Permian Basin contains an estimated 46.3 billion barrels of technically recoverable oil and more than 280 trillion cubic feet of gas. At current production rates this would allow clearly more than twenty years of development, which means that resource scarcity is unlikely to limit activity in the foreseeable future.
Drilling activity, however, remains highly sensitive to oil prices. When prices are constructive operators drill more wells and complete more projects. When prices fall new drilling is often delayed or scaled back. TPL’s growth therefore follows the broader price cycle because the company does not control the pace at which operators develop its land.
To estimate TPL’s growth, I built three scenarios that reflect different market conditions. The numbers are based on the company’s historical performance and on studies from the IEA (World Energy Outlook) and EIA (Drilling Productivity Report) that forecast how drilling activity may evolve in different price environments.
In the base case, which assumes stable energy prices and normal development patterns in the Permian, I expect annual earnings growth of around 10%. I assign this outcome a probability of 50%.
In a stronger environment, where prices rise and operators expand drilling at a faster pace, growth can reach roughly 19%. This scenario receives a probability of 30%.
In a weaker environment, where prices soften and drilling slows, growth can decline by about 8% for a period of time. I assign this bear case a probability of 20%.
Combined, these assumptions result in an expected long term growth rate of roughly 10%, even though actual results will continue to fluctuate with the cycle and in some years land well above or below this level.
In summary the explosive momentum of the past decade is unlikely to return, because TPL has already built out its major business segments and no longer grows from a near zero base. Still the company should be able to deliver continued but moderate growth over time.
How strong is TPL’s profitability?
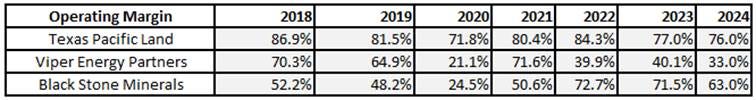
The strong operational momentum of the past decade naturally raises the question of whether this performance also shows up in the company’s profitability. To set the stage, let us briefly recall the core of TPL’s business model: TPL does not drill wells, operate rigs or manage high cost production facilities. All capital intensive work is carried out by the oil companies that lease the land. TPL provides access, surface rights, water infrastructure and broader infrastructure, receiving either a percentage of the revenue or fixed fees in return. This structure keeps operating expenses extremely low. The financial results that follow from this setup are remarkable. Gross margins stand at roughly 100% because the company has no direct production costs. Over the past decade operating margins have averaged around 80%.
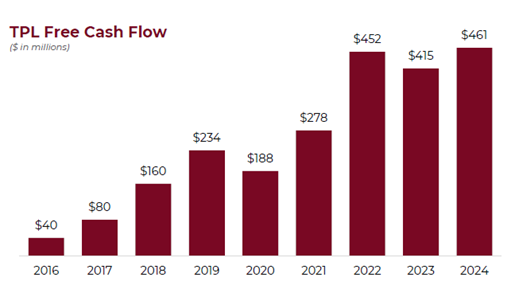
At the same time the business requires very little capital expenditure, which results in exceptionally low capital intensity. Maintenance capital expenditure on land is effectively zero, and the water segment requires only about 10 to 20 million dollars per year to maintain its assets. That’s why free cash flow has increased steadily as basin activity expanded, and over the last five years the company achieved a free cash flow margin of roughly 58%. Put simply, TPL is a real cash machine.
This combination of low costs and low capital requirements means that even in periods of weaker production the company remains comfortably profitable. Normal fluctuations in drilling activity do not come close to pushing TPL into losses.
The strength of the business model also becomes visible when we look at the ROIC. TPL generated an average ROIC of around 114% over the past five years, placing it among the most capital efficient companies I have ever analyzed.
It is also worth noting that TPL is effectively debt free. Net debt currently stands at approximately negative 500 million dollars, which adds another layer of financial strength to an already highly profitable business.
There is little more to analyse here. The outstanding profitability of Texas Pacific Land is a direct result of its unique business model, and the numbers leave no room for doubt. Now that we have confirmed the company’s profitability, the next step is to examine how TPL allocates its capital.
Where does all the cash go?
As we saw in the previous chapter, TPL is a genuine cash machine. This naturally raises the question of how management intends to deploy the cash the company generates.
Management has set a target cash balance of around seven hundred million dollars. This level is meant to ensure operational flexibility and provide a buffer for normal business needs. Everything above this target is intended to flow back to shareholders through dividends and share repurchases. In addition, management plans to use excess cash for a small number of selective land acquisitions, which will then be developed and monetized in the same way as the existing portfolio. Beyond these activities, the company sees no need to retain additional capital.
The shareholder return profile reflects this approach. In 2024 the dividend was increased for the twenty first consecutive year and supplemented by a special dividend. While the current yield of roughly 0.6% appears low, dividend growth has been exceptional, averaging about 36% per year over the last decade and around 18% over the past three years. With a payout ratio of roughly 31% there is plenty of room for further increases, and the company regularly distributes excess cash through additional special dividends. TPL also repurchased shares during 2024, reinforcing its commitment to returning surplus capital to shareholders.
It becomes clear that the company is fully focused on distributing excess capital to its shareholders, whether through dividends or buybacks, rather than accumulating cash on the balance sheet or pursuing larger investments.
We have now seen the extraordinary business model, the growth prospects, the exceptional returns and the way the company allocates its capital. What we have not answered yet is just as important: which risks come with this model and at what price the stock becomes attractive for long term investors.
What could go wrong?
Every company, no matter how robust it may be, naturally comes with risks, and Texas Pacific Land is no exception. There are several important factors worth highlighting.
A central point is that TPL has very little influence over the factors that drive its revenue. This applies especially to the price of oil and gas. The company also can’t influence how much operators decide to drill or how quickly they develop land. When drilling activity rises, royalties, surface payments and water volumes increase. When activity slows, these income streams ease just as quickly. This becomes particularly visible in periods of lower prices, because shale wells decline rapidly and operators adjust their plans much faster than in long cycle offshore projects.
„As we are a significant landowner in the Permian Basin and not an oil and gas producer, our revenue is affected by the development decisions made by companies that operate in the areas where we own royalty interests and land. Accordingly, these decisions made by others affect not only our share of production volumes and produced water disposal volumes, but also directly impact our surface-related income and water sales.“ - Tyler Glover (CEO)
A further risk lies in long term demand. As discussed in the growth chapter, the global energy system is changing. The balance between oil producers and consumers depends on many factors, including efficiency gains, industrial demand and global trade. At the same time a long term shift toward renewable energy and electric mobility could reduce the need for oil in some sectors and therefore influence prices. How these trends evolve will play a major role in determining future drilling activity in the Permian and, in turn, TPL’s revenue streams.
Another area of risk is regulation and environmental oversight. The Permian relies heavily on water, both for drilling and for handling produced water that returns to the surface. Parts of the region already face restrictions due to small earthquake activity, and further tightening of water and disposal rules would mainly affect the operators but would indirectly slow the activity that TPL depends on. Broader rules around emissions, flaring or reporting requirements follow a similar pattern. Texas remains generally supportive of energy development, but stricter federal or local regulation can still create meaningful headwinds.
In summary, TPL faces both short and long term risks, and many of the forces behind them lie outside the company’s control, which makes the business heavily dependent on external decisions and market conditions.
What is TPL actually worth?
After looking at the company in detail, it is time to turn to valuation and determine the price at which an initial position in Texas Pacific Land might be attractive. Given the cyclical but generally steady nature of the business, a DCF model is the most suitable method.
Before moving to the numbers, we need to bring the main assumptions together. In the growth chapter we developed three scenarios and assigned probabilities to each. Based on the weighted outcome of these scenarios, I use an annual growth rate of 10% and a perpetuity growth rate of 2%.
At the profitability level I apply a free cash flow margin of 60%, which is slightly below the most recent value (65%) but still slightly above the long term average of 58%.
For the discount rate, I rely on Damodaran’s current data set, using a cost of equity of 8.4%, a cost of debt of 5.8% and a WACC of 8%.
Putting all of these inputs into the model results in a fair value of roughly 608 USD per share. Applying a margin of safety of 20% results in a preferred entry point to 486 USD per share. Compared with the current market price, this suggests a mispricing of roughly 43%.
Under these assumptions I view the company as clearly overvalued.
Final Thoughts
In summary, Texas Pacific Land is a fascinating company with a unique business model and a clear competitive moat. The last decade was defined by exceptional growth, but the business is now entering a more mature phase in which growth will naturally slow. Even so, the underlying model remains incredibly attractive. The company operates as a true cash machine with extraordinary profitability, making it particularly appealing for investors who value strong and steadily rising dividends.
At the same time it is important to remember that the company is highly dependent on developments in the oil market and on the decisions made by the operators drilling in the Permian. This creates a certain level of uncertainty and volatility in both results and share price performance. Despite that, the long term outlook stays compelling as long as activity in the basin remains healthy and the company continues to generate substantial cash flow.
Reminder: Nothing you read here is financial advice. I am sharing my personal opinions and research, not telling you what to buy, sell, or hold. I am not a financial advisor, and this newsletter should never be seen as a recommendation to invest in any security.
Great post. I like the fact that 85% of the write-up was centered on what truly matters: the business model and industry dynamics. Valuation doesn't substitute for understanding the company like a private owner would.
I'm not the biggest fan of catalysts but yours are simple and more importantly, have sensible probabilities attached.
This post made me a subscriber and I look forward to reading more from you.
Bonus points for having Rollins on your buy list in another post😅
Thanks a lot for the post. Congratulation for the great work done!
I see the strenght of the company in the FCF, the net debt, and the growth. On the contrary, the scarce dividend seems to me like there is no dividend at all, because is close to zero, and even with the expected growth I believe it will keep been too low.
What makes me be cautious about buying the stock is the high PER (around 50) and the high (P/FCF).
Great company, but maybe too expensive right now?